QUICK ANSWER
Can you get an urgent cash loan in Malaysia within 24 hours?
Possibly, depending on the provider and application — but “24 hours” does not automatically mean guaranteed approval or guaranteed funds within 24 hours.
The phrase may refer to a platform that accepts applications 24/7, a processing target, an approval timeframe or disbursement after approval. These are different stages.
Check what the advertised timing meansTIMING IS NOT ONE EVENT
What can “24 hours” actually mean?
| What you see | What it may mean |
|---|---|
| Available 24 hours | Applications can be submitted online at any time. |
| 24-hour processing | A stated target for processing eligible applications within a period. |
| 24-hour approval | A decision may be made within the stated timeframe. |
| Same-day disbursement | Approved funds may be transferred after the required process is completed. |
| Instant loan | Marketing or search terminology, not automatically instant approval or payment. |
24 hours: application → approval → funds
- 01
Apply
Submit information through an official website or app.
- 02
Verify
Identity and application information may need checking.
- 03
Assessment
The provider evaluates the application against its criteria.
- 04
Offer & documents
Review the amount, tenure, cost, payment and terms.
- 05
Disbursement
Approved funds are transferred after the applicable requirements are completed.
- Approval is the decision on your application.
- Disbursement is the transfer of approved funds; actual receipt may occur later.
A 24-hour application, 24-hour approval and 24-hour disbursement do not mean the same thing.
Ask whether the clock starts at submission, complete information, approval or document completion — and when funds are expected to reach the account.
Read the conditions behind the headline
For example, CIMB Cash Plus notes 5 and 6 limit instant approval to selected CIMB@Work segments with more than three months of consistent payroll credits. Instant disbursement is restricted to the stated active CIMB accounts. Both remain subject to the bank’s approval.
DECISION BEFORE SPEED
Need cash today? Start with these four questions
Urgency can make speed feel like the only thing that matters. Use this 4P framework to compare your options more clearly.
01 / Purpose
How much do you actually need?
Start with the expense you are trying to cover, rather than the maximum available. A larger amount creates a larger repayment commitment.
02 / Payment
Can the payment fit your real budget?
Consider rent, food, transport, existing commitments and room for unexpected expenses.
03 / Price
How much will it cost altogether?
Review the amount, tenure, interest or profit rate, charges and total amount payable — not just the monthly payment.
04 / Provider
Who are you dealing with?
Use official channels, verify the provider, read terms and keep records. Do not give an OTP, PIN or password to another party.
For a budget check, the government portal describes MyBijak Kewangan (AKPK) as a financial education and planning service with personal budget simulators. Use it to understand cash flow, not to determine financing eligibility.
See a worked total-cost comparisonQUICK DECISION CHECK
Can you answer all five before continuing?
0 / 5Use these checks to identify what is still unclear.
MYKAD & eKYC
Can you apply for an urgent loan using MyKad?
MyKad can be used for identity verification, but it does not automatically mean it is the only information required.
Identity
MyKad / NRIC and selfie or eKYC verification.
Personal information
Required contact and personal details.
Financial information
Income, employment or information used in assessment.
Banking
Verified bank-account information.
Supporting information
Additional documents where requested.
Actual requirements depend on the provider and product. Do not send MyKad copies or sensitive information to an unverified person or account.
Understand how MyKad is used in an applicationVERIFY FIRST
Are urgent online loans safe?
Online financial services can be legitimate, but urgency can also increase exposure to scams and misleading promises. Check the provider and channel before continuing.
Red flags
- “Guaranteed approval” or “100% approved”.
- Requests for an OTP, PIN or password.
- Unclear provider identity.
- No written terms to review.
Official channels first
- Check the domain spelling and official app.
- Identify who is offering the product.
- Read the offer and keep communication records.
- Verify first, share information second.
Verify through the right official source
- Institutions within BNM’s remit: Use the directory linked from BNM — Financial Scams. BNM explains that an unlisted entity does not necessarily fall within its remit. Choose the check for the provider category.
- Kredit Komuniti in Peninsular Malaysia: KPKT — i-KrediKom supports licensed-company searches for this category. This check does not cover every type of financing provider.
- Suspicious accounts or phone numbers: PDRM recommends Semak Mule before a transaction. Use it as an additional check; no recorded match is not proof of licensing or a safety guarantee.
Already sent money to a suspected scammer?
Immediately contact your bank’s fraud hotline and NSRC on 997, then lodge a police report. Keep transfer receipts and relevant messages.
PDRM — NSRC 997 (26 May 2026) states that the hotline operates round the clock.
UP TO THIS POINT
You have been comparing loans.
“Urgent cash loan”, “instant loan” and “24-hour loan” describe the need. Those search terms do not necessarily describe the structure of every available product.
ANOTHER STRUCTURE
Consider Shariah-compliant personal financing
A conventional loan is not the only structure you may encounter in Malaysia. The practical decision still requires clarity on the amount, payment, tenure, cost, provider and terms — but the financial structure differs.
| Area | Conventional loan | Shariah-compliant financing |
|---|---|---|
| Product structure | Lending arrangement | Applicable Islamic financing contract |
| Cost | Commonly interest | Commonly an agreed profit |
| Contract | Conventional lending | Depends on the Shariah structure |
| One Islamic structure | — | Tawarruq / Commodity Murabahah |
| Review | Rate, payments, fees and terms | Profit, payments, charges, structure and terms |
Read the agreement to understand the financing structure and your payment commitment.
Explore Shariah-compliant personal financingUNDERSTAND THE STRUCTURE
What is Tawarruq?
Tawarruq involves commodity sale-and-purchase transactions that generate cash proceeds for the customer. Commodity Murabahah is a cost-plus-agreed-profit sale with a deferred selling price.
- 01
Commodity purchase
The financing provider purchases a commodity.
- 02
Commodity Murabahah
The commodity is sold to the customer at a deferred price comprising cost and agreed profit.
- 03
Sale to a third party
The customer sells to a third-party buyer, or appoints an agent under the financing documents.
- 04
Financing proceeds
The customer receives cash proceeds from the commodity sale.
Structure reference: BNM — Commodity Murabahah / Tawarruq
JOMDANA-i
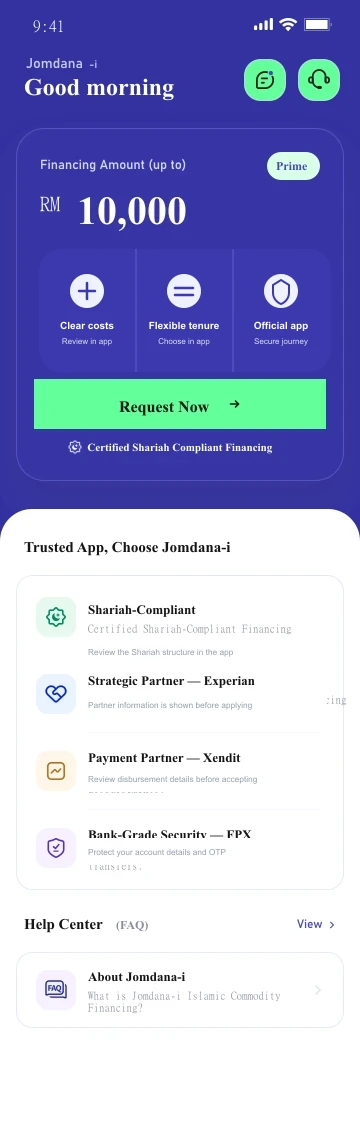
Looking for this type of financing? Meet Jomdana-i.
Now that you understand urgent-loan search terminology and Shariah-compliant financing, you can compare whether Jomdana-i fits your needs.
Jomdana-i is Shariah-compliant personal financing using Tawarruq / Commodity Murabahah.
- Amount
- Up to RM10,000
- Planner tenure
- 3–24 months
- Application
- Digital & identity verification
- Outcome
- Subject to assessment
PLAN BEFORE YOU REQUEST
How much financing are you considering?
Use the planner to see how amount, tenure and illustrative monthly payment work together. Check the profit rate, charges and total amount payable in the actual offer.
JOMDANA-i FINANCING PLANNER
See how amount and tenure work together.
ESTIMATED MONTHLY PAYMENT
RM 422.92APPLICATION GUIDE
How does a Jomdana-i application work?
These eight checkpoints explain the Jomdana-i digital application journey. Follow the app instructions and current financing documents.
- 01
Register
Start through the Jomdana app or an official channel.
- 02
Verify identity
Complete NRIC and selfie verification through eKYC.
- 03
Complete details
Provide the requested personal, employment and bank-account information.
- 04
Financing assessment
The application is subject to financing and risk assessment.
- 05
Review an option
Where available, review the amount, tenure, payment and terms.
- 06
Financing documents
Complete the applicable digital documents.
- 07
Tawarruq
Commodity transactions are completed under the financing structure.
- 08
Disbursement
After requirements and processes are completed, approved proceeds go to the verified account.
Current process reference: Jomdana FAQ. Timing depends on complete information, verification, assessment and operations.
Explore Jomdana-i ↗BEFORE YOU DECIDE
Urgent does not have to mean rushed.
- NeedDo I genuinely need this amount?
- TimingWhat does “today”, “fast” or “24 hours” mean?
- AffordabilityCan I realistically manage the payment?
- CostDo I know the total amount payable?
- ProviderHave I verified the party and channel?
- StructureConventional loan or Shariah-compliant financing?
- TermsHave I read the offer and agreement?
If existing payments are already difficult to manage, consider advice before adding another commitment. The government portal describes AKPK counselling as helping people understand financial difficulties, spending patterns and affordability, and prepare budgets and debt-management strategies.
FAQ
Frequently asked questions about urgent cash loans in Malaysia
Can I get an urgent cash loan today in Malaysia?+
Some providers offer fast or fully digital application processes, but receiving funds on the same day is not automatically guaranteed. Timing depends on verification, assessment, documentation and disbursement.
What does “24-hour loan” mean?+
It may refer to 24/7 application availability, a processing target, decision timing or disbursement timing. Confirm which stage and conditions the provider means.
Does a 24-hour loan guarantee money within 24 hours?+
No. A stated timeframe does not automatically guarantee approval or disbursement. The application remains subject to the relevant process and assessment.
Is instant approval guaranteed for urgent loans?+
No. Approval depends on the provider and applicable assessment criteria, even when the application process is simple or digital.
Can I use only MyKad to apply?+
MyKad may be used for identity verification. eKYC, personal details, employment or income information, bank-account details and supporting documents may still be required.
What should I check before choosing a fast loan?+
Check the amount, repayment affordability, total cost, tenure, provider, application requirements, approval process and actual disbursement terms.
Are urgent online loans safe?+
Safety depends on the provider and channel. Use official websites or apps, verify the provider and do not disclose an OTP, PIN or password to another party.
How do I check a provider?+
Choose the check for the provider category: BNM’s directory for institutions within its remit, or i-KrediKom for licensed Kredit Komuniti companies in Peninsular Malaysia. Semak Mule is an additional check on suspicious accounts or phone numbers, not proof of licensing or a safety guarantee.
What should I do if I have already sent money to a suspected scammer?+
Immediately contact your bank’s fraud hotline and NSRC on 997, then lodge a police report. Keep transfer receipts and relevant messages. PDRM states that 997 operates round the clock; reporting does not guarantee recovery of funds.
What is the difference between a loan and Shariah-compliant financing?+
A conventional loan uses a lending arrangement, while Shariah-compliant financing uses the applicable Islamic financing contracts. Tawarruq / Commodity Murabahah is one structure. Review the actual agreement.
What is Tawarruq?+
Tawarruq involves commodity purchases and sales that generate cash proceeds for the customer. Implementation depends on the product, contracts and applicable Shariah arrangement.
Is Jomdana-i an urgent cash loan?+
No. Jomdana-i is Shariah-compliant personal financing, not a conventional cash loan. Consider the structure, affordability, assessment and terms before requesting financing.
Is Jomdana-i Shariah-compliant?+
Official Jomdana information describes Jomdana-i as Shariah-compliant financing using Tawarruq / Commodity Murabahah under its Shariah governance framework. Refer to current product documents.
How much financing is available through Jomdana-i?+
Current product information displays financing of up to RM10,000. Available amounts depend on assessment, product options and current terms.
Is Jomdana-i approval guaranteed?+
No. Every application is subject to the applicable financing assessment and criteria. Planning or calculating payments does not determine approval.
YOUR NEXT STEP
Need personal financing?
If Shariah-compliant personal financing matches your needs, explore Jomdana-i and review the amount, tenure and terms before deciding.