QUICK ANSWER
Can you get an instant loan without documents in Malaysia?
An online application can reduce paperwork, but providers may still request identity and income information for verification. “Instant” may describe the application rather than when a decision is made or funds arrive. Some providers accept alternative income evidence; check the requirements for the product you choose.
UNDERSTAND THE TERMS
What do “instant” and “without documents” mean?
These terms can describe different parts of an application. Here is how to read them.
- Without a payslip
- A provider may accept other income evidence, such as bank statements. Ask what the product accepts.
- Without documents
- The process may use digital forms and verification. Identity and income details may still be requested.
- Instant or 24 hours
- The term may refer to application access, decision time or disbursement. Check which stage it describes.
- Using MyKad
- MyKad helps verify identity. A provider may also request other information to assess the application.
For more on application and funding times, read our urgent financing guide.
WHAT TO PREPARE
What information can you prepare?
Having the following information ready makes it easier to check requirements with a provider. Accepted documents vary by product.
Identity
MyKad and personal details for verification.
Income
Income records or bank statements showing incoming funds.
Work or business
Details of your employment, self-employment or business.
Bank account
Details of a bank account in your own name.
Supporting information
Any other documents requested by the provider.
Identity verification helps a provider identify the applicant; income and existing commitments help it assess affordability. The application requirements explain what you need to provide.
Understand how MyKad is used in an applicationINCOME DOCUMENTS
No payslip? How to prepare alternative income records
A payslip is one way to show income. If you are self-employed, earn commissions or run a small business, other records can help explain how you earn. The evidence accepted depends on the provider.

Bank statements and payment records
Bank statements can show money entering and leaving your account. If customers or platforms pay you through a bank, organise statements alongside relevant payment records so the source of income is clear. Ask the provider which statement period it needs.
Self-employment or business records
Invoices, receipts, sales records or business documents can help explain your activity. Gig workers and freelancers can also gather platform earnings summaries and customer payment records to discuss with a provider.
Income that changes from month to month
If your income changes, review several months of records to understand the pattern. Separate business revenue from the costs of earning it, then consider what remains after living expenses and existing commitments. This can help you plan a payment that fits your budget.
For example, a freelancer can organise customer payments alongside related invoices, while a business owner can gather bank statements and sales records. If you are paid in cash, ask the provider which records are suitable for your situation.
For example, some banks list bank statements and business registration documents for self-employed applicants. See the requirements published by Maybank and Public Islamic Bank. Each provider sets its own requirements; for Jomdana-i, refer to the app or official channels.
BEFORE YOU CHOOSE
How to compare options when looking for a loan without documents
A convenient application process is one consideration. To make a more informed choice, also look at the amount you receive and the commitment throughout the financing period.
Purpose & amount
Identify what you need the money for and the amount that meets that need.
Scheduled payment
Check each payment amount and due date against your income pattern.
Tenure & cost
Review the number of payments, rate, charges and total amount payable.
Provider & terms
Identify the provider, official channel and offer documents before deciding.
Look at the total, not just the monthly payment
A smaller monthly payment may come with a longer tenure. Compare both the payment due each month and the total amount payable over the full term. Check whether any charges are listed separately.
- Net cash received
- RM2,000
- Scheduled payments
- RM380 × 6 = RM2,280
- Fees paid separately
- RM20
- Total commitment
- RM2,300
In this example, the difference between net cash and total commitment is RM300. Fees already included in payments or deducted before cash is received are not added again. This is a made-up example to explain the calculation; actual offer figures and terms vary.
To check the figures in your own offer, use the offer cost checker or read the personal financing guide.
CHECK THE PROVIDER
Choose a provider you can verify
Use the provider’s official website or app and verify who you are dealing with before sharing information. For Kredit Komuniti companies in Peninsular Malaysia, i-KrediKom can help you check a licence.
Keep your OTP, PIN and passwords private. If you suspect a scam, contact your bank or NSRC on 997 promptly.
FINANCING OPTIONS
Explore Shariah-compliant financing
Alongside conventional loans, Shariah-compliant financing offers a structure based on Islamic financing contracts. One structure is Tawarruq / Commodity Murabahah, which uses commodity transactions to generate cash proceeds for the customer.
Compare the amount you need, payments, tenure, charges and terms when choosing an option.
Learn how Tawarruq worksUNDERSTAND THE STRUCTURE
How does Tawarruq work?
Tawarruq uses commodity transactions to provide cash proceeds. Here is a simplified view of the flow.
- Provider purchases a commodity
The provider obtains a commodity from a supplier.
- Sale to the customer
The commodity is sold to the customer at an agreed deferred price.
- Sale to a third party
The commodity is sold to a third-party buyer for cash.
- Proceeds and payment
The customer receives cash proceeds and pays the deferred price under the financing terms.
The selling price, agreed profit and payment obligations are set out in the financing documents. The execution and any agency arrangements depend on the product and contracts.
Bank Negara Malaysia’s explanation of Tawarruq · Read the Tawarruq guide.
JOMDANA-i
Meet Jomdana-i
Jomdana-i is Shariah-compliant personal financing based on Tawarruq / Commodity Murabahah. Explore product information and the digital application process through Jomdana’s official channels.
Check the current requirements and prepare the information requested. Each application is subject to assessment and financing terms.
Explore Jomdana-i ↗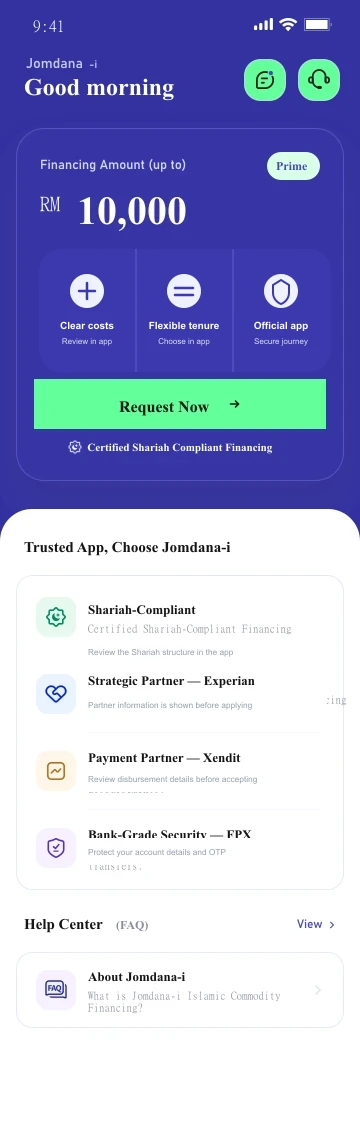
APPLICATION PROCESS
How do you start a Jomdana-i application?
You can start digitally through the Jomdana app. Here are the main things to prepare and review along the way.
As part of general financial preparation, you can also learn how to read CTOS and CCRIS reports to identify entries that need checking or correcting. Actual application requirements remain specific to the provider and product.
- Register in the app
Download the Jomdana app and register with an active mobile number.
- Verify your identity
Complete identity verification using your MyKad and selfie as requested in the app.
- Provide your information
Enter the personal, employment and bank-account details requested. Additional supporting documents may be needed.
- Review the financing
Follow the in-app process and review the amount, payments, tenure and financing documents before agreeing.
- Follow the status
The application goes through financing assessment. Check the app or official channels for updates.
Follow the app instructions for the current sequence. For more information, see the Jomdana FAQ.
FAQ
Frequently asked questions
Can I apply without a payslip?
Some providers accept alternative proof of income. Check the available options and document requirements with your chosen provider.
What can I use as alternative proof of income?
Depending on the provider, bank statements, income records or business documents may help show your income.
What does an application without documents mean?
It may describe a digital process or different documentation requirements. Providers can still request information for verification and assessment.
How long does an online financing application take?
Timing depends on the provider, complete information, verification and assessment. Check whether a stated timeframe refers to applying, the decision or receiving funds.
Is MyKad the only information needed?
MyKad is used for identity verification. A provider may also request income, employment or bank-account information, or supporting documents, for assessment.
Can self-employed people apply for financing?
Self-employed people can explore suitable products and check what income evidence is accepted. Requirements and assessment depend on the provider and product.
What if my income changes each month?
Organise your available income records to show the pattern of incoming funds, then compare the proposed payments with your expenses and commitments.
What should I check in a financing offer?
Check the net amount received, each monthly payment, tenure, rate, charges and total amount payable. Read the financing documents and terms too.
Is Jomdana-i Shariah-compliant financing?
Yes. Jomdana-i is Shariah-compliant personal financing based on Tawarruq / Commodity Murabahah. See the Jomdana-i page for current product information.
How is an application assessed?
Each application is assessed using the information provided and current financing criteria. Approval is not guaranteed.
YOUR NEXT STEP
Ready to explore your options?
Learn more about Jomdana-i, then review the information and terms for your needs.
View Jomdana-i ↗For identity verification and application information, see the guide to financing with MyKad.