QUICK ANSWER
What should you check before choosing personal financing?
Check at least five things: the amount needed, an affordable payment, the financing tenure, the total cost and the product structure. Two offers for the same amount may not create the same commitment.
Suitable financing is not necessarily the option offering the highest amount. It should fit your needs, budget and terms you understand.
AMOUNT
How much do you actually need?
PAYMENT
What fits your monthly budget?
TENURE
How long will the commitment last?
COST
What are the rates, charges and total payment?
STRUCTURE
Conventional or Shariah-compliant?
COMPARE CLEARLY
How to compare personal financing options
Do not focus on one number alone. A lower regular payment may come with a different tenure, while a higher amount can create a larger commitment than you genuinely need.
| Compare | Question to ask |
|---|---|
| Financing amount | Is this the amount I genuinely need? |
| Regular payment | Does this payment fit my budget? |
| Tenure | How long will I make payments? |
| Profit rate / cost | How is the financing cost presented? |
| Charges | Which charges apply and when? |
| Total amount payable | What will I pay overall? |
| Structure | Do I understand how the product is structured? |
Do not just ask, “Which one is cheapest?”
Which option is clearest in terms of amount, affordability, cost and structure for my situation?
START WITH THE NEED
How much do you actually need?
Instead of starting with “What is the maximum I can get?”, ask “How much do I genuinely need for this purpose?”. Calculate that need first and avoid choosing a larger amount simply because it is available.
PERANCANG PEMBIAYAAN JOMDANA-i
Lihat hubungan antara jumlah dan tempoh.
ANGGARAN BAYARAN BULANAN
RM 422.92Ilustrasi ini menggunakan logik yang sama seperti kalkulator Jomdana-i semasa: bahagian keuntungan dikira sebagai 1.5% daripada bahagian pembiayaan bulanan. Ia bertujuan untuk perancangan sahaja dan bukan kadar keuntungan efektif, tawaran pembiayaan, keputusan kelayakan atau jaminan kelulusan. Kadar, bayaran dan terma sebenar tertakluk kepada penilaian, tawaran yang berkenaan serta dokumen pembiayaan semasa.
UNDERSTAND THE TERMS
Personal loan vs personal financing: what is the difference?
In Malaysia, personal loan and personal financing are often used for a similar search purpose. However, the products behind those terms do not necessarily use the same structure.
| Area | Conventional loan | Islamic financing |
|---|---|---|
| Product basis | Loan | Shariah contract / structure |
| How cost is described | Interest | Profit rate |
| Shariah structure | Not applicable | Depends on the product |
| Example structure | — | Tawarruq / Commodity Murabahah |
| Still compare | Payments, tenure, costs and terms | Payments, tenure, costs, terms and structure |
Changing the terminology alone does not make a product Shariah-compliant. Check the actual structure, contracts and product documents.
For a broader starting point before comparing financing terms.
Read the personal loan Malaysia guide →CHECK AFFORDABILITY
How much can comfortably fit into your budget?
Being able to make one payment does not mean the commitment is manageable throughout the tenure. Look at what remains after essential expenses and other commitments.
This is a planning tool, not an official eligibility formula. Ask whether you will still have reasonable room for daily expenses, savings and unexpected costs after all commitments are paid.
BNM discusses a broader affordability approach for providers under its framework, including sufficient remaining income for essential living expenses. See BNM Annual Report 2025.
BEFORE APPLYING
Are you ready to apply?
Actual requirements vary by product and provider. After understanding the amount and affordability, check eligibility and what you may need to provide.
BEFORE ACCEPTING AN OFFER
Understand the real cost before accepting an offer
Receiving an offer does not mean you need to accept it immediately. Look beyond the amount you will receive.
Financing amount
Is the amount still aligned with your original need?
Regular payment
Can it fit into your budget after essential expenses?
Tenure
How long will the payment commitment last?
Profit rate / cost
How is the cost presented in the documents and offer?
Charges
Which charges apply and under what circumstances?
Total amount payable
What is the complete picture of your commitment?
CONSIDER CAREFULLY
Consider carefully before applying if…
- you are not sure how much you need
- the payment is not included in your budget
- you repeatedly need new financing for a monthly cash shortfall
- you plan to pay old commitments without a clear plan
- a small income change could make payment difficult
- you do not understand the rates, charges and total amount
The goal is not to obtain the largest amount. It is to make a decision you understand and can manage.
SHARIAH-COMPLIANT FINANCING
Looking for Shariah-compliant personal financing?
If Shariah principles matter to you, do not stop at the word “Islamic”. Check the actual structure. One structure used is Tawarruq / Commodity Murabahah.
Tawarruq, in simple terms
- A commodity is purchased
- Sold to the customer at a deferred price
- Sold to a third party
- Financing proceeds are received
For Jomdana-i, commodity trading is facilitated through Sedania as the commodity trading platform provider.
JOMDANA-i
Consider Jomdana-i
Jomdana-i is Shariah-compliant Islamic Commodity Financing using Tawarruq / Commodity Murabahah.
The current product page displays financing of up to RM10,000. Before making a request, check the amount, tenure, payment, profit rate, charges, total amount payable, documents and terms.
Available amounts, eligibility and terms are subject to financing assessment and current product terms. Approval is not guaranteed.
Download Jomdana ↗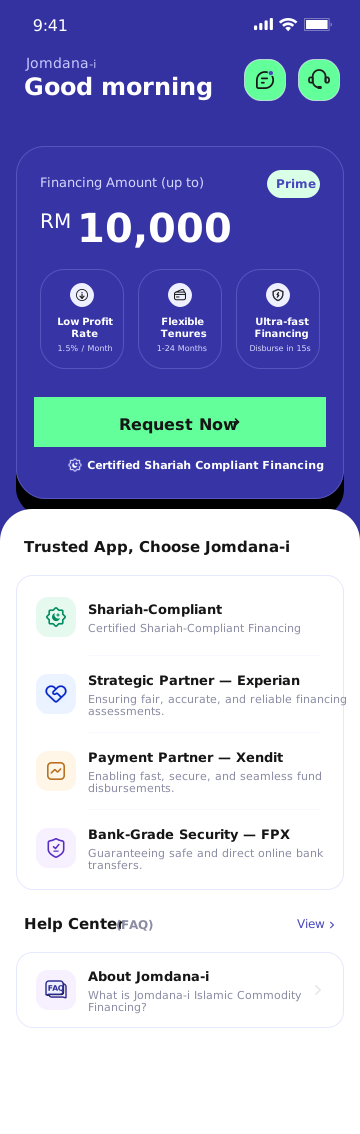
SAFETY
Before sharing information for an application
- Use the official website or app.
- Never share your OTP, PIN or password.
- Do not send information to numbers or accounts you cannot verify.
- Know who is receiving your information.
- Read the documents and terms before agreeing.
- Understand how personal information is handled.
IN SUMMARY
How should you choose personal financing?
Start with the amount you genuinely need and check whether payments can fit your budget. Compare the tenure, profit rate or cost, charges and total amount payable. Review eligibility, documents and product structure. If you want Shariah-compliant financing, understand the structure before proceeding.
A suitable option is one you understand, can compare and can manage.
FAQ
Frequently Asked Questions About Personal Financing
What is personal financing?+
Personal financing is a financing facility for personal needs, subject to the product structure, the provider’s criteria and the applicable terms. Before applying, review the amount, payments, tenure, costs and how the product is structured.
What is the difference between a personal loan and personal financing?+
Both terms are commonly used by people looking for funds for personal needs, but the underlying product structures may differ. For Islamic personal financing, check the Shariah structure and contracts used in addition to the payment amount, tenure and costs.
How should I compare personal financing options?+
Start with the amount you genuinely need. Then compare affordability, tenure, profit rate or financing cost, applicable charges, total amount payable and the financing structure.
What should I check before applying for personal financing?+
Check your affordability, eligibility requirements, the information or documents required, the costs involved and the applicable product terms. Make sure you understand the commitment before proceeding.
Is all personal financing Shariah-compliant?+
No. If you are looking for Islamic personal financing, check whether the product clearly states the Shariah structure and contracts it uses.
What structure does Jomdana-i use?+
Jomdana-i is Shariah-compliant Islamic Commodity Financing based on Tawarruq / Commodity Murabahah. The commodity trading process is facilitated through Sedania.